
What financial requirements apply to foster parenting?
Foster parenting does not require you to be wealthy or a homeowner, but you must show that your household can manage its existing financial commitments without relying solely on fostering payments. As part of the assessment, your fostering service will review your income, regular outgoings, savings and debts, and explain the allowance and other financial support available.
Partnering with an
Ofsted Outstanding Provider
Foster parenting does not have a set minimum salary or savings threshold. The key financial requirement is that your household can meet its normal commitments independently, while fostering payments are used to support the child’s day-to-day care and recognise the responsibility of fostering.
During the assessment, your fostering service will consider your overall financial position rather than looking at one figure in isolation. This normally includes:
- regular income from employment, self-employment, pensions or benefits;
- mortgage, rent, council tax, utilities, insurance and other household bills;
- loans, credit commitments, child maintenance and other regular payments;
- outstanding debts, arrears or repayment arrangements;
- savings and access to emergency funds; and
- the likely additional costs of caring for a foster child.
You may be asked to provide documents such as payslips, bank statements, benefit information, mortgage or tenancy details, loan statements and evidence of other income or expenditure. The purpose is to establish that your finances are stable and that you understand the financial responsibilities involved. Financial information is considered as part of the wider assessment, alongside your circumstances, health, household arrangements and ability to meet a child’s needs.
Do you need to be in full-time employment? No. Foster carers may have different income arrangements, including part-time work, self-employment, pensions or benefits. However, your income must be sufficient for your household’s existing commitments. If fostering would require you to stop work or reduce your hours, the service will discuss how this could affect your budget and whether the expected fostering payments are appropriate to rely on.
What if you have debts or limited savings? Having a mortgage, rent, loans or other debts does not automatically prevent you from fostering. The important questions are whether repayments are up to date, whether your commitments are manageable and whether your household would remain financially secure if circumstances changed. Significant arrears, insolvency, unresolved financial problems or dependence on borrowing may need further consideration. Be open about these matters so the assessment can consider the full position accurately.
How do fostering payments work? Fostering services provide an allowance for each child placed with you. This is intended to contribute towards the child’s food, clothing, personal items, travel, activities and other everyday needs. Some services may also provide additional payments linked to the child’s age, needs, training or the type of placement. The amount and structure vary, so ask the service for its current allowance policy rather than relying on general figures found elsewhere.
Fostering payments should not be treated in the same way as an ordinary wage. Placements can change, and payments may depend on whether a child is living with you and the terms of the placement. You should prepare a household budget that remains workable without assuming a particular number of placements or a particular payment level. The service can explain how allowances are paid, which expenses may be covered separately and what records you need to keep.
Fostering income may receive specific tax treatment, but the rules depend on your circumstances and can change. Ask your fostering service for current guidance and consider taking independent advice from HM Revenue and Customs or a qualified tax adviser. Do not assume that all payments are taxable or tax-free without checking the rules that apply to you.
Before applying, list your monthly income and essential outgoings, review any repayment plans and identify costs that could increase when a child joins your household. During the assessment, give complete and accurate information about your finances. A clear budget helps you and the fostering service decide whether your circumstances are suitable and what financial planning may be needed before approval.
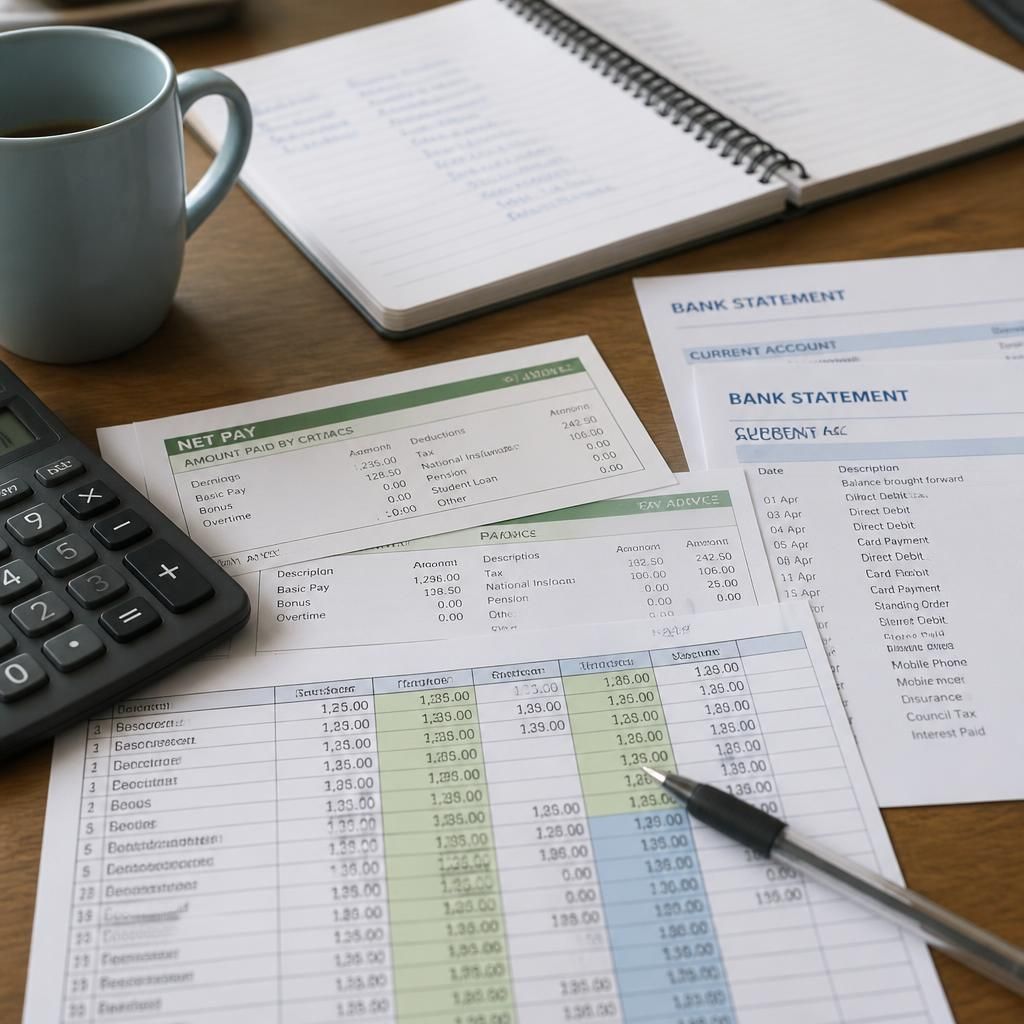
Before making major household changes, such as reducing your working hours or taking on new financial commitments, make sure you understand how fostering could affect your budget. Approval does not set a universal payment level, and the amount paid can depend on the placement and the fostering service’s policy.
If you foster as part of a couple or shared household, discuss how essential bills will be managed and ensure everyone understands which costs relate to caring for the child. Asking the service to explain its payment arrangements and expense procedures in writing can help you make informed financial decisions before applying.
Discuss your financial eligibility for foster parenting
If you are considering fostering, contact Become A Foster Family to discuss your financial circumstances and the information needed for an application. Our team can explain the assessment process and help you understand the financial arrangements that apply.