Become A Foster Family

Foster Carer Pensions

A foster carer pension is a way to build retirement provision alongside your fostering income. Options may include personal pensions, workplace pensions and State Pension entitlements, with tax planning helping you assess what suits your circumstances.

Start Your Journey Today

Partnering with an
Ofsted Outstanding Provider

The Practical Impact of Fostering

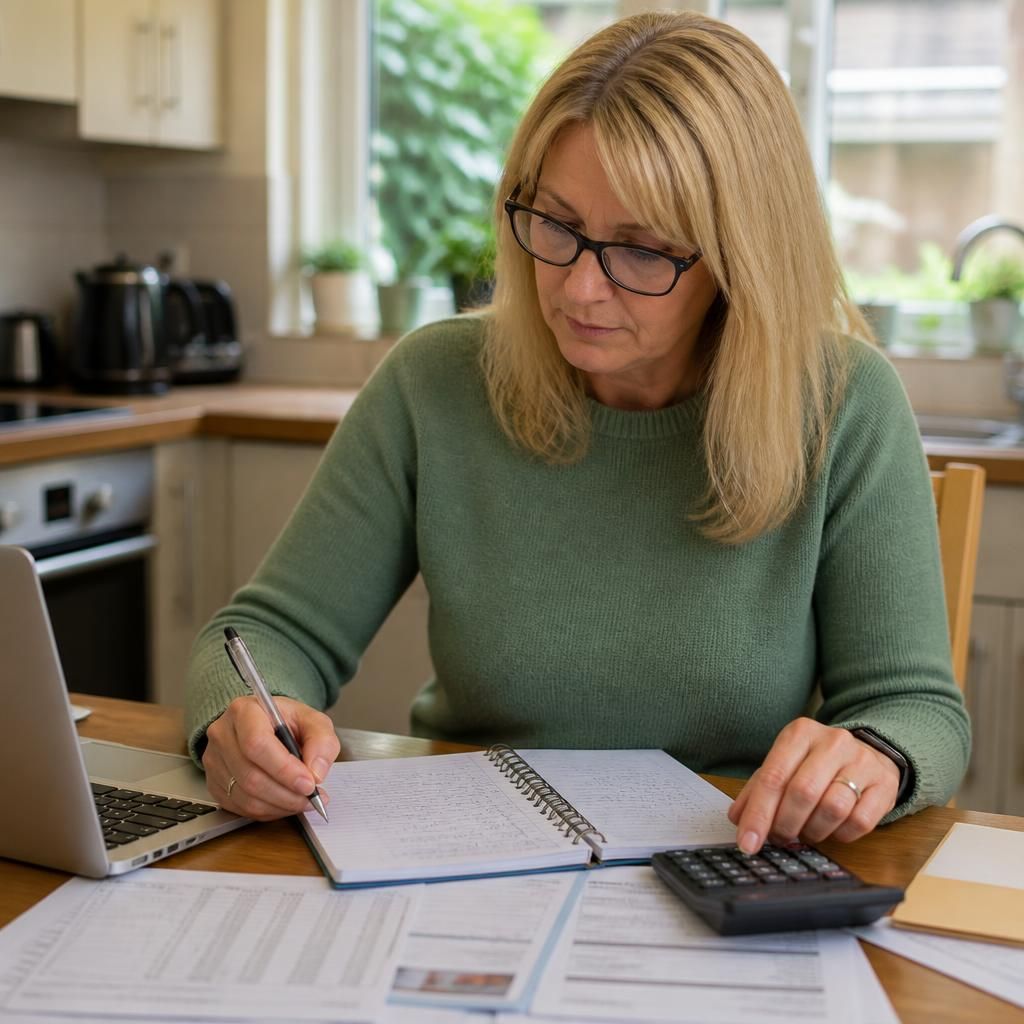
Foster carer reviewing pension documents and household finances

Map pension choices around fostering income

Fostering income may vary according to your circumstances, so pension planning needs to sit alongside your wider household budget. Listing regular commitments and deciding what contribution level feels manageable can help you assess your options without losing sight of the costs of caring.

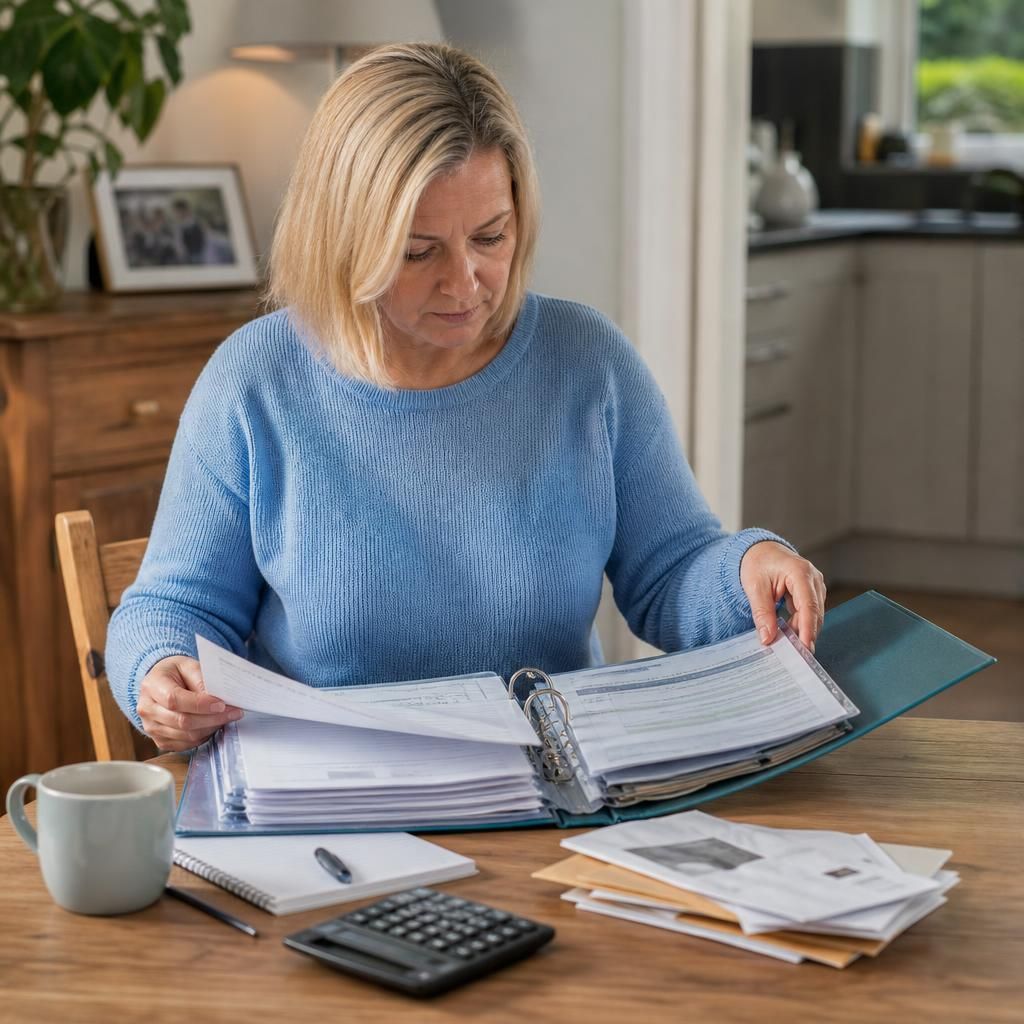
Foster carer organising financial records and pension paperwork

Keep clear records from the start

Keep statements, contribution details and information about any existing pensions together. Well-organised records can make it easier to understand your retirement position and identify what may need reviewing if your fostering arrangements change.

Couple discussing long-term financial planning at home

Include fostering in household decisions

Pension planning can affect shared financial decisions, particularly where one person changes their working pattern to foster. Discussing contributions, outgoings and longer-term priorities can help everyone understand how fostering fits into the household’s plans.

Foster carer speaking with a professional financial adviser

Understand advice before making changes

A regulated financial adviser can help you compare personal pension arrangements, workplace pensions and other retirement provisions. Ask how advice is paid for, what assumptions are being made and whether recommendations take your fostering income and wider circumstances into account.

Foster carer reviewing financial plans after a change in circumstances

Review plans when circumstances change

A new placement, a change in fostering responsibilities or a return to other employment may alter how you manage pension contributions. Reviewing your arrangements after a significant change helps you check that your records, contributions and longer-term plans still reflect your situation.

Pension Planning for Different Fostering Circumstances

Your pension choices may differ if you are employed alongside fostering, share caring responsibilities with a partner, are approaching retirement, or expect your fostering role to change. Consider each household’s existing provisions before selecting a route.

Fostering alongside employment

If you remain employed while fostering, review your workplace pension alongside any personal provision. Check how contributions, employer payments and your planned working pattern fit together before changing either arrangement.

Couples sharing responsibilities

Partners may have different pension records, contribution histories and retirement plans. Consider each person’s arrangements separately, then discuss how household income and caring responsibilities could affect future contributions.

Approaching retirement

If retirement is closer, check your State Pension record and understand when existing pensions can be accessed. A regulated financial adviser can explain the options, risks and tax implications for your circumstances.

Changing your fostering role

Your pension planning may need reviewing if you pause fostering, reduce your fostering commitments or stop altogether. Keep records of existing pensions and revisit contributions when your income or caring responsibilities change.

One Foster Carer’s Pension Planning Journey

A foster carer pension is retirement saving made through personal contributions, rather than an automatic benefit linked to fostering. One carer explained that this distinction helped them treat pension planning as a separate household task, alongside reviewing income and outgoings.

They gathered details of previous arrangements, checked contribution records and noted how much they could set aside regularly. Keeping documents together helped them discuss options with an independent financial adviser, including charges, flexibility and access.

They reviewed contributions during household budgeting and kept fostering-related tax records together. This routine did not replace regulated advice, but gave them a clearer basis for decisions as their circumstances changed over time.

Questions to Ask Before Choosing a Foster Carer Pension

How will fostering affect my existing pension arrangements?

Check your National Insurance record and State Pension forecast separately: fostering payments do not automatically establish workplace pension membership, so consider voluntary contributions or private provision with regulated financial advice.

Are foster carer pension contributions tax deductible?

Personal pension contributions are not usually deducted from fostering payments as business expenses. Tax relief may apply differently, depending on your circumstances and pension type; seek regulated financial advice first.

What happens to my pension if I stop fostering?

If you stop fostering, personal pension savings usually remain yours, but future contributions may change. Review payment arrangements, access rules, and tax implications with a regulated financial adviser before acting.

What pension charges should foster carers check?

Check pension charges including administration, investment management, advice, transfer and withdrawal fees. Compare how each is applied, whether charges are fixed or percentage-based, and their effect on projected retirement income.

Real Experiences of Foster Carer Pension Planning

Foster carer reviewing a State Pension forecast and retirement documents

Checking Existing Pension Entitlements

One foster carer began pension planning by checking their State Pension forecast and gathering information about previous workplace schemes. This gave them a clearer picture of what provision was already in place before considering further contributions. Reviewing the record also helped them identify questions for a regulated financial adviser, including whether any gaps or missing information needed attention.

Foster carer discussing pension options with a financial adviser

Getting Regulated Financial Advice

A foster carer found that professional advice helped separate general pension information from decisions specific to their own circumstances. They prepared details about household income, existing arrangements, planned retirement age and access needs before the appointment. This made it easier to compare personal pension options, charges, flexibility and contribution choices without treating general guidance as a personal recommendation.

Foster carer adding pension contributions to a household budget

Fitting Contributions Around Household Finances

One household reviewed its regular outgoings before deciding whether pension contributions were affordable alongside fostering-related costs. Rather than committing to an amount based on assumptions, they considered how contributions would work during changes in income and expenditure. Recording the decision in their household budget made future reviews more straightforward.

Foster carer organising pension statements and tax records

Keeping Pension and Tax Records Together

A foster carer kept pension statements, contribution information and fostering-related tax records in one organised file. This did not determine which pension arrangement was suitable, but it made information easier to provide when seeking advice and completing financial reviews. Keeping records current also reduced the risk of overlooking an old workplace or personal pension.

Foster carer reviewing pension arrangements after a change in circumstances

Reviewing Plans When Circumstances Change

Another carer treated pension planning as an ongoing task rather than a one-off decision. They reviewed their arrangements after changes to household finances and considered whether contribution levels, pension objectives or retirement plans still matched their circumstances. Any changes to the pension itself were discussed with a regulated adviser, while fostering guidance helped them understand which financial questions to raise.

Key Pension Considerations for Foster Carers

Foster carer pension planning means understanding how retirement income is built when fostering payments do not operate like an employer’s pension scheme. Different sources have their own rules.

The boxes below explain contribution choices, tax treatment and how fostering income can fit into longer-term planning. The right approach depends on existing provision, household circumstances and intended retirement plans.

Personal Pension

A personal pension can provide a separate arrangement for retirement saving, with contributions and investment choices set according to your circumstances and the provider’s terms.

Workplace Pension

If you also have employed work, check how its workplace pension operates, including contributions, employer payments and what happens if your working pattern changes.

State Pension Record

Your State Pension entitlement is based on your National Insurance record, so review that record separately from any private pension arrangements.

Tax Treatment

Tax relief and contribution rules depend on your income, tax position and the type of pension, so confirm how fostering payments affect your own planning before contributing.

Investment Risk

Pension contributions are commonly invested, meaning their value can rise or fall; consider the level of risk and how it fits your intended retirement timeframe.

Review Retirement Plans

Revisit your pension choices when your household circumstances, fostering role or expected retirement plans change, and check current access rules before making decisions.

Foster Carer Pension Questions Answered

What pension options are available to foster carers?

Foster carers can usually contribute to a personal pension, subject to provider rules and their circumstances. Independent financial advice can clarify eligibility, contributions, tax treatment and suitable arrangements for retirement.

How much should foster carers contribute to a pension?

There is no universal contribution: base it on affordability, existing retirement provision and desired income, then confirm provider minimums, tax relief and affordability with regulated financial advice for your circumstances.

Can foster carers build State Pension entitlement?

State Pension entitlement depends on your National Insurance record. Foster carers may qualify for National Insurance credits in certain circumstances; check your record and eligibility with GOV.UK or an adviser.

Can foster carers join a workplace pension?

A workplace pension may apply if you have employment alongside fostering, subject to eligibility and earnings rules. Fostering itself does not ordinarily create workplace pension membership; check with your employer.

Talk Through Your Foster Carer Pension Questions

If you are considering a foster carer pension, speak with our team about your circumstances. We can help you identify the questions to raise, understand how fostering fits your wider plans, and consider an appropriate next step without pressure.

Talk To Our Team