
Are fostering allowances separate from self-employed earnings?
Yes. Fostering allowances are separate from any income you earn through your own self-employed work, although fostering payments have specific tax rules and should be recorded separately from your business income.
Partnering with an
Ofsted Outstanding Provider
The two income streams are treated separately: money received for fostering relates to the care of a child or young person, while earnings from your own self-employed work arise from the goods or services you provide to customers. They should therefore be identified separately in your records, even if both are paid into the same bank account.
A fostering payment may contain different elements, such as money intended to contribute towards the child’s day-to-day costs and a fee or professional payment for the care provided. The exact description depends on the fostering arrangement and the organisation making the payment. It is important to keep the payment information supplied by the fostering service, local authority or agency, as this will help you understand what each payment represents.
Fostering payments have their own tax treatment under HMRC rules. Qualifying foster carers may be able to use qualifying care relief, which is designed to recognise the costs involved in providing care. This means the calculation is not necessarily the same as the calculation used for profit from a separate self-employed business. The amount of relief and the records needed can depend on factors such as the type of care provided and the fostering arrangements in place.
This does not mean that every amount connected with fostering can automatically be ignored for tax purposes. You should establish how your particular payments must be reported and keep the relevant documentation. A tax adviser or HMRC can explain how the current rules apply to your circumstances, particularly if you also run a business, have more than one fostering arrangement or receive other forms of income.
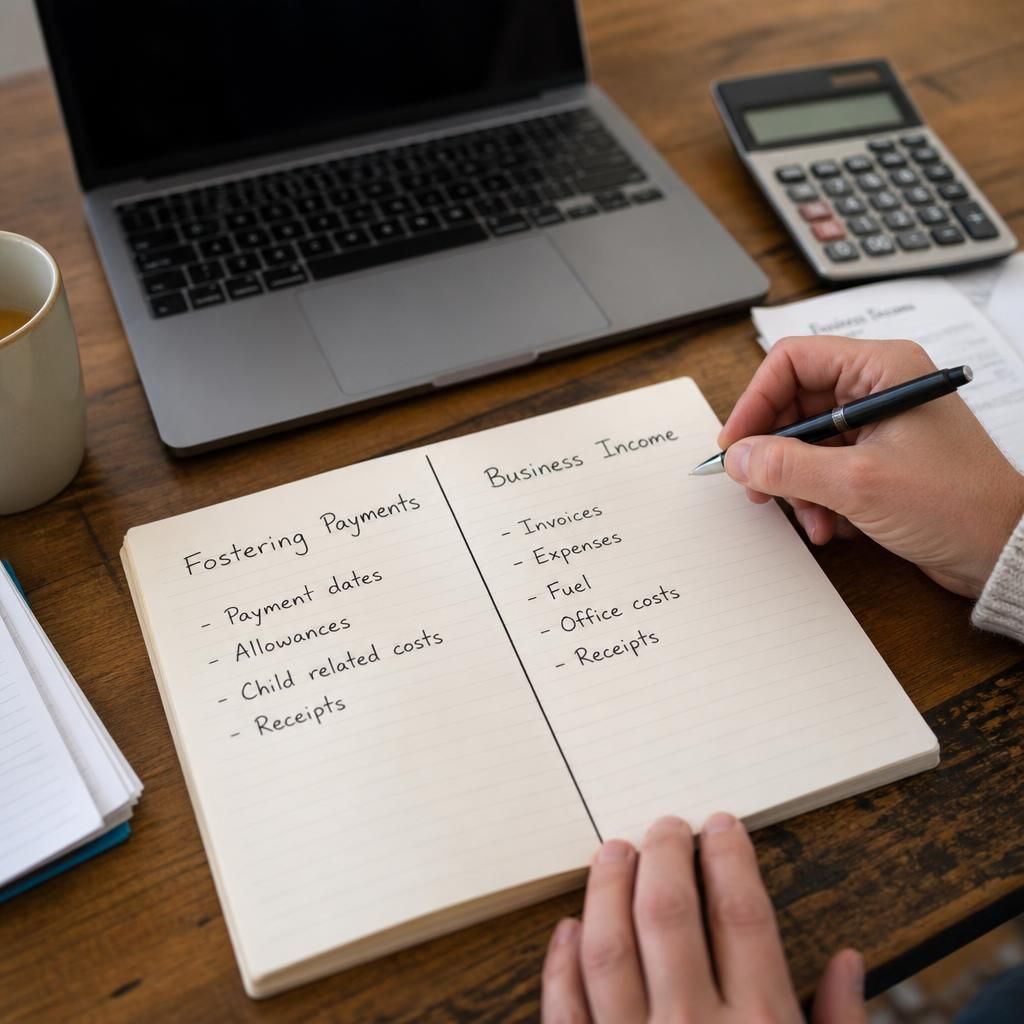
For practical record-keeping, keep fostering information apart from your business accounts. Useful records include:
- payment statements or remittance advice from the fostering service;
- the dates and amounts received for each fostering arrangement;
- receipts for costs connected with caring for a child or young person;
- invoices, sales records and business expenses relating to your separate self-employed work; and
- notes explaining how shared costs have been divided between fostering and business use.
A separate bank account is not necessarily required simply because you foster and work for yourself, but using one can make the distinction easier to maintain. If you use one account for everything, mark each payment and expense clearly when it is recorded. Avoid relying on bank statements alone, because they may not explain whether a transaction relates to fostering, your business or personal spending.
Shared household costs need particular care. For example, a cost may have a fostering purpose, a business purpose, or both. If it relates partly to your self-employed work and partly to fostering, use a reasonable and consistent method to apportion it. Do not claim the same expense twice, and do not treat ordinary personal spending as a business cost merely because you foster from home.
Your self-employed accounts should show the income and allowable expenses of that business only. Fostering receipts should not be added to your business turnover simply because you are registered as self-employed or complete a self-assessment tax return. Equally, having a separate fostering payment does not remove your responsibility to declare ordinary trading income and meet the record-keeping requirements for that work.
It is also worth checking whether fostering payments affect any means-tested benefits, tax credits or other financial arrangements you have. Those systems can apply their own definitions and reporting rules, which may differ from the rules used for income tax. If your circumstances change, obtain specific advice before submitting a return or reporting your income.
Before applying, ask the fostering service what payments you would receive, how they are described, and what statements or summaries it provides. During the assessment and once approved, discuss your record-keeping arrangements with your accountant or tax adviser. Keeping the two types of income distinct from the beginning makes it easier to complete accurate accounts and provide the right information when it is requested.
Fostering allowances and self-employed earnings may arrive on different schedules, so plan your household cash flow around each income stream separately. A fostering payment may follow the terms of your fostering agreement, while business income may depend on when you complete work, issue invoices and receive payment from customers.
This distinction is particularly important if you reduce your self-employed workload to meet the needs of a child or young person. Do not assume that fostering payments will replace every day-to-day business earning or that your business income will remain unchanged during a placement. Consider how your working hours, customer commitments and childcare responsibilities will fit alongside fostering before you apply.
Keep your business pricing, invoices and customer agreements based on the work you provide, rather than including any fostering payment in those calculations. If a placement changes the amount of work you can accept, review your business arrangements and discuss the financial implications with an accountant or tax adviser.
Discuss fostering allowances and self-employed income
If you are considering fostering alongside self-employed work, speak with our fostering team about your circumstances and the financial questions to raise before applying.