
What happens to a pension when a foster carer changes agency?
Changing fostering agency does not usually cancel or automatically transfer a personal pension: savings already built up generally remain with the existing pension provider, while contributions linked to the former agency stop. Before moving, check whether the new agency offers any pension-related arrangement and ask your pension provider or a regulated financial adviser whether any action is needed.
Partnering with an
Ofsted Outstanding Provider
A change of fostering agency can affect how future pension contributions are arranged, but it does not by itself rewrite the terms of pension savings already built up. The practical outcome depends on whether you have a personal pension, an arrangement connected with your former agency, or separate workplace pension savings from other employment.
Personal pension arrangements
If you pay into a personal pension, self-invested personal pension or other individual arrangement, the policy normally remains in your name when you leave an agency. You can usually leave the existing savings where they are, subject to the provider’s terms, or consider changing the investment or transferring the pension. A transfer is a separate decision and should not be made simply because you have changed agency.
Check the policy documents before making changes. Older pensions can contain valuable features, such as guaranteed benefits, protected pension ages or specific charging arrangements, which may be lost on transfer. Some providers may also apply exit charges or require certain steps before accepting a transfer. Your pension provider can explain the existing terms, while a regulated financial adviser can assess whether transferring is suitable for your circumstances.
Contributions connected with the former agency
If the former agency made payments into a pension arrangement, or you paid contributions through a scheme it facilitated, establish exactly what happens when your fostering agreement ends. Ask for a final contribution statement and check that all payments due have been credited. Confirm whether the arrangement becomes paid-up, remains open for personal payments, or requires you to contact the provider directly.
Do not assume that an arrangement associated with one agency will automatically continue when you join another. Fostering agencies may have different ways of supporting carers with pension planning, and a new agency may not use the same provider or contribution process. Obtain the terms in writing and compare them with your existing arrangements before deciding whether to consolidate anything.
State Pension and National Insurance
Your State Pension is separate from a private or personal pension. It is based on your National Insurance record, so changing agency does not transfer private pension savings into the State Pension or move an existing private policy. However, a change in your work and income can affect how National Insurance is dealt with. Foster carers should check their individual position, particularly where fostering is their main source of income, because tax and National Insurance treatment can depend on their circumstances.
Request a State Pension forecast and review your National Insurance record through the relevant government service. If you are unsure whether contributions or credits are due, obtain guidance from HM Revenue and Customs or a suitably qualified adviser. A fostering agency cannot determine every part of your personal State Pension position.
Tax relief on new contributions
When you start paying into a pension after changing agency, check how tax relief will be claimed. The provider may add basic-rate relief automatically, while any additional relief may need to be dealt with through Self Assessment, depending on your tax position. Foster care income has specific tax rules, and the amount treated as relevant earnings for pension purposes may not be the same as the total amount paid to you. Keep records of contributions and ask a tax adviser if you are uncertain about what can be claimed.
Changing agency may also alter the timing or level of fostering payments. Avoid setting a contribution that is difficult to maintain simply because the previous arrangement used a different payment method. Review the amount after you understand your new income, allowable expenses and other financial commitments. If contributions need to stop temporarily, ask the pension provider what effect this will have on charges, benefits and the eventual retirement value.
A sensible checklist before moving
- List every pension you hold, including personal pensions and pensions from previous employment.
- Obtain current valuations, annual statements and details of charges, investment choices and any special benefits.
- Confirm the date and amount of the last contribution made through the former agency.
- Ask whether any agency-linked arrangement will remain open, become paid-up or require a new payment instruction.
- Ask the new agency whether it offers any pension-related arrangement, and request the eligibility rules and contribution details.
- Check the payment method, bank details and reference information for any new personal contributions.
- Review your nominated beneficiaries with each pension provider, as these nominations are not necessarily updated when you change agency.
- Keep copies of statements and correspondence so that you can identify missing contributions later.
Before transferring or combining pensions, compare the costs, investment options, retirement benefits and access rules rather than choosing solely for convenience. If the pension contains safeguarded or guaranteed benefits, regulated financial advice may be required or particularly important. The new agency can clarify its own fostering arrangements, but it cannot replace advice about whether a pension transfer or contribution strategy is right for you.
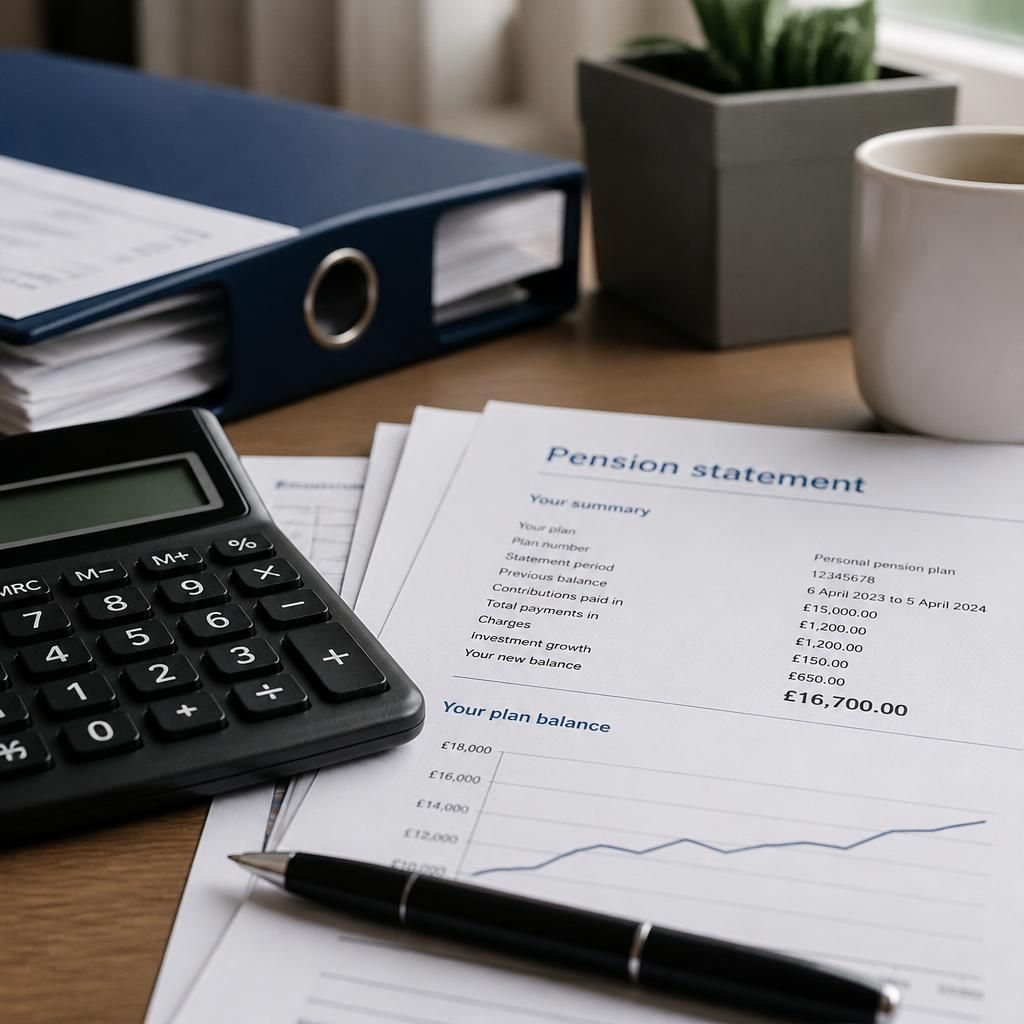
A change of fostering agency does not normally require you to close your pension account. The key step is to identify which organisation is responsible for each payment: the former agency, the new agency or you personally. Your pension provider’s statement is the definitive record of money credited to the policy, so use it rather than an agency payment summary when checking your balance.
If a payment appears to be missing, contact the provider with the contribution date, amount and payment reference, then ask the relevant agency to investigate its records. Keeping these documents together can help distinguish a delayed contribution from a change in the way payments are made after you move.
Ask about pension arrangements when changing fostering agency
Speak to our fostering team about how pension-related arrangements work before changing agency, so you can compare your options with a clear understanding of the process.