
What pension charges should foster carers check?
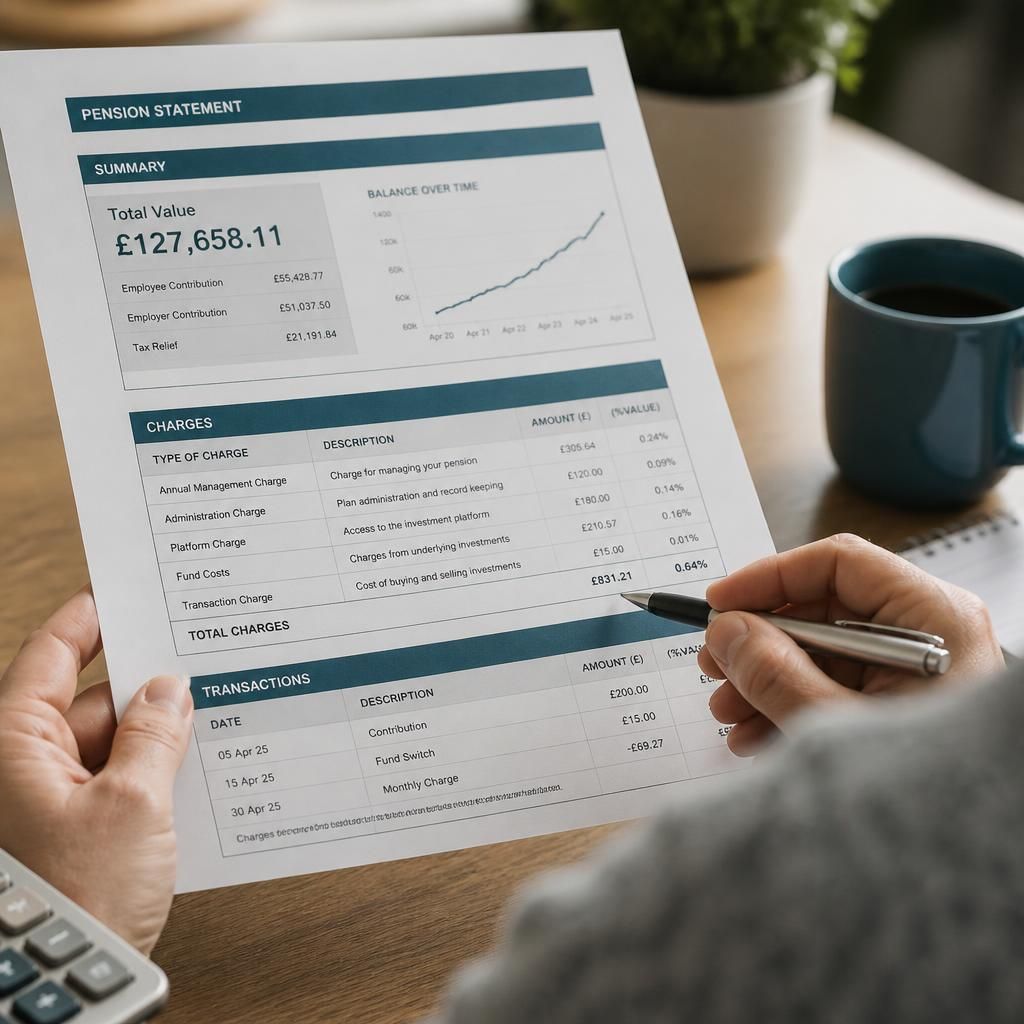
Foster carers should check the pension’s annual management, administration, platform, fund, advice, transaction, transfer and exit charges. Compare how each fee is calculated, when it is taken and what services it covers, because charges reduce the amount remaining invested for retirement.
Partnering with an
Ofsted Outstanding Provider
Pension charges should be checked in the scheme’s key information, illustration and terms and conditions before you start contributing, and reviewed if your pension or investment choices change. The important question is not simply how much a pension costs, but which deductions apply, how they are calculated, when they are taken and whether they provide a service you need.
Look beyond the headline fee. A quoted annual percentage may cover only the pension wrapper or administration. The investments held inside it can have their own ongoing fund costs, while a financial adviser may charge separately for advice. Ask for the total cost of using the pension with the particular funds and options you are considering, rather than relying on a single advertised figure.
- Check whether charges are fixed or percentage-based. A fixed amount can represent a larger proportion of a small pension pot, while a percentage charge increases as the pot grows. Some arrangements use a combination of both.
- Find out when deductions are made. Charges may be taken from contributions, the pension balance, investment returns or a separate account. This affects how much is invested and makes it easier to compare arrangements on a like-for-like basis.
- Check for different rates at different pot sizes. Some providers apply tiered pricing or reduce a charge once the pension reaches a particular value. Confirm whether any reduction happens automatically and what happens if the balance later falls.
- Ask what is included. Establish whether the stated cost covers online access, statements, investment switching, beneficiary nominations, retirement administration and routine support. Services described as optional may carry an additional fee.
Examine the investment costs. The fund’s ongoing cost can vary depending on whether you choose, for example, a managed fund, a tracker fund or a fund with additional features. There may also be costs within the fund that are not presented in the same place as the pension’s administration fee. Read the fund factsheet and check whether the quoted cost includes all relevant underlying expenses.
Ask about advice charges separately. If an adviser recommends a pension or reviews it for you, request a written explanation of the initial and ongoing advice fees. Confirm whether these are paid directly or deducted from the pension, whether ongoing advice is optional and what service continues for the ongoing fee. You should also ask about the cost of advice if you stop using the service.
Check transaction and switching costs. Moving between funds, buying or selling investments, changing the investment strategy or making certain withdrawals can create dealing or transaction costs. These may not appear as a regular line on a pension statement. Ask how often they apply and whether there are any limits on free switches.
Understand transfer and exit conditions. Before transferring an existing pension, check whether the current arrangement has a transfer fee, exit charge, market value adjustment or valuable benefits that could be lost. A new pension with a lower annual charge may still be unsuitable if leaving the old arrangement triggers a substantial cost or removes guarantees. Do not transfer solely because a comparison shows a lower headline fee.
Check charges when taking benefits. Some pensions charge for setting up drawdown, taking a lump sum, purchasing an income or making repeated withdrawals. Ask for the cost of each retirement option you may realistically use, including whether charges apply per transaction or as an ongoing deduction.
Consider your contribution pattern. Foster carers may want flexibility when deciding how much to pay into a pension. Check whether the arrangement charges for stopping, reducing, restarting or varying contributions, and whether a minimum payment applies. This is particularly important if your contributions may not be the same each month.
Request a clear comparison. Ask the provider or adviser to show the effect of all charges on the projected pension value using the same contribution level, investment assumptions and retirement date as any alternative being considered. Treat projections as illustrations rather than guarantees. Compare the total pounds deducted as well as the percentage rate, because a small difference in an annual rate can affect a pension over many years.
Keep the key features document, fund information, fee schedule and annual statements together. Review statements for unfamiliar deductions, changes to the charging structure and fees that have appeared after changing funds or accessing benefits. If a charge is unclear, ask the provider to explain its amount, frequency, calculation method and the service it covers in writing before making a decision.
A pension charge may be permanent, conditional or temporary, so check whether the fee quoted applies throughout the arrangement. Some providers use introductory pricing, waive a charge for a limited period or offer a lower rate only while particular conditions are met. The cost after any concession may be the more relevant figure for a long-term retirement plan.
- Ask whether the quoted charge is a standard rate or a temporary offer.
- Check when a discounted rate ends and what charge will apply afterwards.
- Find out whether the fee changes if you alter your investments, stop contributing or move into retirement.
- Ask whether any waiver depends on maintaining a minimum contribution, balance or selected service.
Keep the provider’s fee schedule with the original illustration so you can identify when a charge changes. If the future cost is not clear, request an example showing the deductions that would apply after any introductory period or change in circumstances.
Get guidance on pension charges before fostering
For general guidance on how fostering may fit alongside your wider financial planning, speak to the Become A Foster Family team and prepare your pension questions for a qualified financial adviser or pension provider.