
How does fostering affect your tax code?
Fostering does not usually change your tax code automatically because qualifying care relief can cover foster care payments, meaning they may not create taxable income. Your tax code could change if HMRC needs to account for other taxable income, benefits or an underpayment, so check any updated notice carefully and contact HMRC if it appears incorrect.
Partnering with an
Ofsted Outstanding Provider
Your tax code is used by an employer or pension provider to calculate PAYE deductions from employment or pension income. Foster care payments do not normally appear as a separate line in that code. The tax treatment of fostering is usually considered through qualifying care relief and, where required, Self Assessment rather than by changing the PAYE code attached to your job.
What a tax code represents
A tax code tells your employer or pension provider how much tax-free income HMRC believes should be available against that particular source of PAYE income. HMRC may amend it when it receives information about your salary, pension, taxable benefits, an estimated underpayment, or a change to allowances and deductions.
For example, a code may change if you start receiving a taxable workplace benefit, begin drawing a pension, change jobs, or HMRC needs to collect tax that was underpaid in an earlier year. The change is applied to the PAYE income linked to the code; it does not necessarily mean that the amount shown on your payslip is your total taxable income from every source.
How fostering fits into the picture
Fostering income is assessed under special rules. Qualifying care relief gives foster carers a specific way to calculate the taxable profit from their fostering work. If the relief covers the relevant foster care receipts, there may be no taxable fostering profit to add to your overall income. This calculation is separate from the tax-free allowance used in a PAYE tax code.
Where a taxable amount remains after applying the relevant relief, it is generally dealt with through the appropriate tax reporting process. HMRC does not necessarily adjust the code for your employment simply because you become a foster carer. A tax code change should therefore not be treated as a complete calculation of the tax due on fostering.
Why HMRC might still change your code
Becoming a foster carer can coincide with other changes in your circumstances, and these may affect your code. HMRC could revise it if, for example:
- your employment income or pension changes;
- you receive a taxable benefit from an employer;
- HMRC has information suggesting that tax was underpaid;
- an allowance or tax relief included in the code is amended or removed; or
- HMRC is using an estimate of taxable income from another source to collect tax through PAYE.
An adjustment connected with another source of income does not automatically mean that all foster care payments are taxable. Check the explanation on HMRC’s coding notice rather than relying only on the number shown in the code.
What to check when your code changes
- Compare the new coding notice with the previous one and look for the income, benefit, allowance or underpayment that caused the amendment.
- Check that HMRC’s estimated figures relate to you and reflect your current circumstances.
- Confirm that your employer or pension provider has received the revised code and that it is being used from the stated date.
- Keep records of fostering receipts, allowable costs and the qualifying care relief calculation, as these may be needed for your tax records even if your PAYE code has not changed.
- Contact HMRC if an item is wrong, duplicated or based on circumstances that no longer apply.
If your fostering arrangements change, such as ending, restarting or altering the type of care you provide, review the figures used in your tax records. A change in the number of placements or payments does not, by itself, explain a PAYE code; the underlying taxable calculation and any other income must be considered together.
It is also possible to have no relevant PAYE tax code if you do not have employment or pension income. In that situation, the fostering tax position is not shown through a payslip code. The important records are the fostering income, the relief available and any required return or payment to HMRC.
Tax rules can depend on your wider circumstances, including other income and whether you foster alone or with another person. If the coding notice does not match your records, ask HMRC for an explanation and obtain tailored advice from a suitably qualified tax adviser before changing how you report your fostering income.
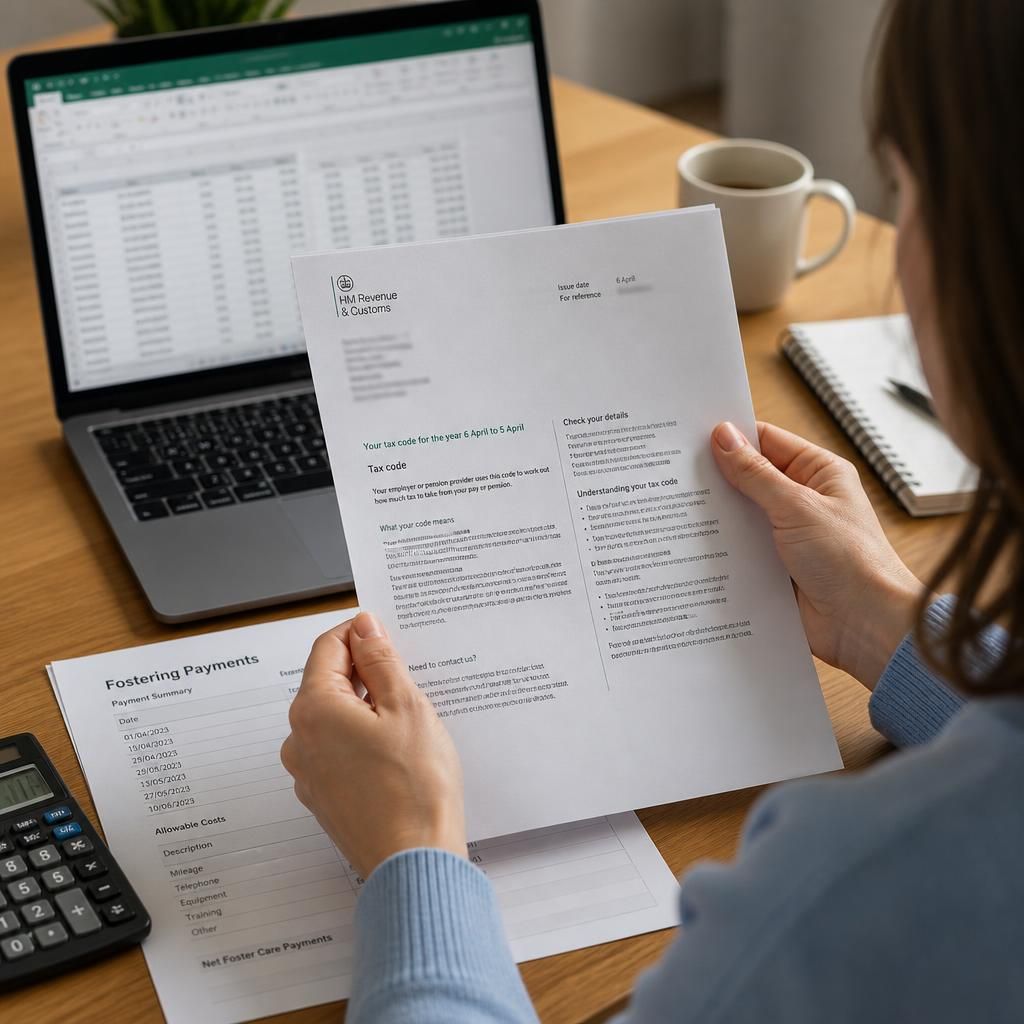
If you have more than one PAYE source, such as employment alongside a pension or a second job, HMRC may divide your available tax-free allowance between them. This means the tax code shown by one employer can look different from the code used for another source, even though both are based on your overall PAYE position.
Check each coding notice against the income source it relates to. A change to one code may alter the tax deducted from that particular payslip without indicating that your fostering payments have been taxed through payroll. If the allocation does not reflect your current employment or pension arrangements, ask HMRC to review the details and keep the revised notice with your tax records.
Learn more about fostering and your tax position
If you are considering fostering, contact Become a Foster Family to learn more about the application process and how to prepare for the financial aspects of fostering.